Public Liability Insurance Broker
Trusted Public Liability Insurance Brokersfor Australian Businesses
500+ 5 Star ★★★★★ Google ReviewsAward-winning BrokersTrusted by thousands of Businesses
Public liability insurance for Australian businesses
Public liability insurance covers your business if a customer, client, contractor, or member of the public suffers injury or property damage because of something your business did — or failed to do. It pays the legal defence costs and any compensation awarded against you, up to the limit of your policy. Without it, these costs come directly from your business.
It is one of the most widely required covers in Australian business — commercial landlords require it as a condition of your lease, principal contractors require it before you step on site, government contracts specify minimum limits, and many licensing bodies require proof of current cover before issuing or renewing a licence. Even where it is not legally required, the financial exposure from a single uninsured public liability claim can be large enough to close a business.
Third-party personal injury
A customer slips and falls in your shop, a site visitor is injured during your construction work, a patient is hurt at your clinic. Public liability covers the legal defence and compensation for bodily injury claims made against your business by people who are not your employees.
Third-party property damage
Your contractor damages a client's flooring, your delivery damages a product at a customer's premises, your excavation undermines a neighbouring structure. Public liability covers claims for physical damage to another party's property caused by your business activities.
Products liability
A product you sell causes injury or illness, food you prepared causes food poisoning, a component you manufactured fails and damages property. Products liability — typically included in a combined PL policy — covers claims arising from goods your business sells or supplies.
What public liability insurance does not cover
Public liability has clear boundaries. Understanding what it excludes is as important as understanding what it covers — these are the exposures that require separate policies.
Employee injuries — injuries to your own employees are covered by workers compensation insurance, which is a separate mandatory policy
Professional advice errors — financial loss caused by incorrect professional advice or services requires professional indemnity insurance
Deliberate or intentional acts — claims arising from intentional damage or deliberate harm are excluded from all public liability policies
Damage to your own property — your own assets, equipment, and stock require commercial property insurance
Asbestos liability — claims arising from asbestos exposure are excluded under most standard public liability policies
Pollution liability — environmental pollution claims typically require a separate pollution or environmental liability extension
Product recall costs — the cost of recalling a product from market is excluded, though the injury or damage it caused before recall is covered
Contractual liability — where you have agreed in writing to accept liability regardless of fault, this assumed liability requires a specific contractual liability extension
What public liability claims actually look like
These scenarios represent the most common public liability claim types across Australian businesses — each one a real category of claim that public liability insurance is designed to cover.
Customer slips on a wet floor
A customer walks into your cafe and slips on a recently mopped floor that was not adequately signed. She falls and breaks her wrist, requiring surgery and six weeks off work. A public liability claim is made for medical costs, lost income, and pain and suffering. Total claim: $85,000. Legal defence costs and compensation covered by the policy.
Tradie damages client property
A plumber working on a bathroom renovation accidentally damages a pipe junction causing water to escape into the client's newly renovated kitchen below. The damage requires full kitchen cabinet replacement and flooring repair. Total claim: $42,000. The plumber's public liability policy covers the full repair cost.
Food poisoning — multiple claimants
A contaminated batch of chicken at a catering event causes food poisoning in fourteen guests. Each guest makes a separate claim for medical expenses and lost income. Total claim across all fourteen claimants: $210,000. Products liability within the combined PL policy covers legal defence and compensation.
Visitor injured on your premises
A client visiting your office for a meeting trips on a loose carpet edge near the reception and fractures their hip. They are elderly and require extended medical care and rehabilitation. Total claim: $165,000. Public liability covers the defence costs and the compensation awarded by the court.
Public liability claims lodged in Australia in the APRA May 2023 analysis period
Average payout for smaller public liability claims — still significant for an uninsured business
Average payout for substantial public liability claims — bodily injury, impacts and falls
Source: APRA Review of claims trends and affordability of public liability and professional indemnity insurance in Australia, May 2023.
Choosing the right public liability limit for your business
There is no single right answer — the correct limit depends on your industry, your contract and lease obligations, and the nature of your business activities. Here are the three things to assess.
Check your contractual and lease requirements first
Before assessing risk, check what your contracts and leases actually require — because these set a minimum floor regardless of your personal risk assessment. Commercial leases almost universally require $10M to $20M public liability as a condition of tenancy. Principal contractor agreements in construction commonly specify $20M. Government and council contracts frequently mandate specific limits. If your contract requires $20M and you hold $10M, you are in breach of the contract and the policy may not respond correctly at claim time.
Assess your actual risk exposure
The size of the claims your business could generate depends on how many people interact with your business, how serious an injury or damage event could be, and how much legal defence costs could escalate before resolution. High foot traffic, work on client premises, and industries with a history of large bodily injury claims all point toward higher limits. The premium difference between $10M and $20M is typically small — the decision to underinsure to save a modest annual premium rarely makes financial sense when weighed against the actual exposure.
Use industry norms as a baseline — then adjust up
Industry norms exist because claims data shows what typical claims in each sector cost. Use the table below as a starting point, then consider whether your specific operation has above-average exposure — a larger venue, more public interaction, higher-risk activities, or higher-value client projects all justify a higher limit than the industry baseline.
Which businesses need public liability insurance?
Any business that interacts with the public, operates on client premises, sells products, or employs people in physical work needs public liability insurance. Here are the most common business types we cover across Australia — click through to the relevant page for industry-specific cover information.
What you need to know about public liability and subcontractors
Subcontracting creates specific public liability issues for both the head contractor and the subcontractor. Here is what each party needs to understand.
Subcontractors must hold their own policy
Your public liability policy covers your business operations. It does not extend to cover a subcontractor's liability for incidents arising from their specific scope of work. Every subcontractor working under you needs their own current public liability insurance — require a certificate of currency before they start, and keep it on file.
Disclose subcontracting to your insurer
Most policies require you to declare the extent to which you use subcontractors at inception and renewal. Undisclosed subcontracting is one of the most common grounds on which construction public liability claims are disputed. If your use of subcontractors has changed, notify your broker rather than waiting for renewal.
Worker-to-worker excess applies
If a subcontractor's employee is injured on your site and makes a claim against your business, your public liability policy may respond — but worker-to-worker claims carry significantly higher excesses than standard third-party claims, commonly $10,000 to $100,000 per event in construction environments.
ABN contractors are not automatic employees
A contractor operating under their own ABN is generally responsible for their own insurance. In very specific circumstances where they work exclusively under your direction and control, an extension may be available — but this requires prior insurer approval and is not automatic. Do not assume ABN workers are covered under your policy without confirming with your broker.
Why use Morgan Insurance Brokers for your public liability insurance?
Going direct to an insurer gives you one option. A broker gives you access to the full market — and the expertise to know which policy actually covers your specific business activities, not just which one is cheapest.
Access to 150+ insurers and specialist underwriters
Many of the specialist underwriters with the most competitive terms for specific industries — trades, hospitality, healthcare, construction — are not available direct to the public. They are only accessible through brokers. We place public liability across the full Australian market, not just the household names that advertise to consumers.
We represent your interests — not the insurer's
An insurer's call centre represents the insurer. A broker represents you — when assessing your risk, when negotiating policy terms, and when a claim is made and the insurer's first instinct is to find a reason not to pay. We advocate on your behalf throughout the policy lifecycle, not just at the point of sale.
Policy wording reviewed for your specific activities
Two policies with the same limit can cover very different things. The exclusions buried in the policy wording — height restrictions for trades, hot works conditions for hospitality, care custody and control exclusions for service businesses — are where the real differences live. We read the wording, not just the headline price.
Full claims management at no extra cost
When a claim is made against your business, we manage the process from lodgement through to settlement — liaising with the insurer, providing documentation support, and advocating for the most favourable outcome. Claims management is included in our service, not charged separately.
Same-day certificates for leases, contracts, and licences
Commercial leases, principal contractor agreements, government contracts, and licensing bodies all require certificates of currency — often urgently. We issue certificates the same day for most public liability requests, in the specific format required by your landlord, client, or licensing body.
Annual reviews as your business changes
Your public liability exposure changes when you take on new contracts, open a new premises, start a new service, hire more staff, or your turnover grows. We conduct annual reviews and advise on limit and wording changes proactively — so your policy keeps pace with your business rather than lagging behind it.
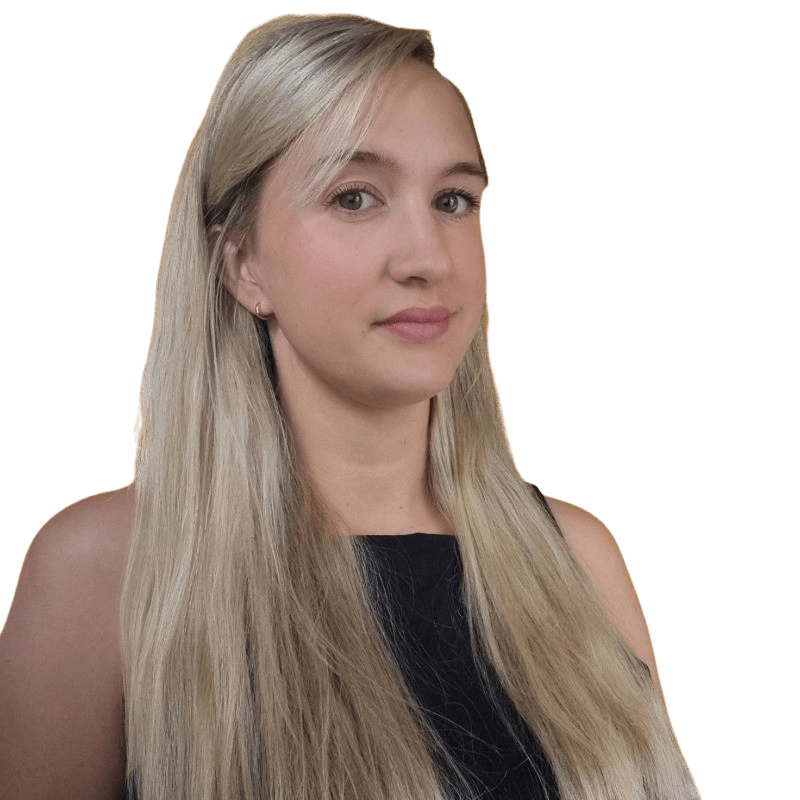
Lauren Spice is the Director of Morgan Insurance Brokers and has arranged public liability insurance for businesses across Australia for over 15 years — from sole traders needing a basic $5M policy to get on a client's site through to large construction companies managing multiple contracts simultaneously with different limit requirements on each project.
The most common problem Lauren finds when reviewing existing public liability policies is a policy wording that contains industry-specific exclusions the client was never told about — height restrictions for trades, hot works conditions for hospitality and food service, or subcontractor disclosure conditions that have never been complied with. Every one of these is a potential claim denial waiting to happen. Lauren reviews the wording, not just the price, and makes sure the policy actually covers the activities your business performs before you need to make a claim and find out it does not.
Public liability insurance FAQs
Is public liability insurance compulsory in Australia?
Public liability insurance is not universally compulsory under Australian law — but it is effectively mandatory for most businesses through contractual and regulatory requirements. Commercial leases almost universally require it as a condition of tenancy. Most principal contractor agreements require subcontractors to hold current PL before accessing site. Government contracts, council permits for events, and many professional licensing bodies specify minimum PL limits as a condition of operation. In practice, operating without public liability insurance means being unable to sign most leases, access most construction sites, or win most commercial contracts.
Some states require specific industries to hold public liability as a licence condition — building contractors, electricians, and plumbers in several states must demonstrate current insurance before a licence is issued or renewed. Tasmania requires a minimum of $5M public liability for all licensed builders.
Does public liability insurance cover me as a sole trader?
Yes — public liability insurance is available to sole traders and is one of the most important covers a sole trader can hold. As a sole trader you have unlimited personal liability — if a claim is made against your business and you are uninsured, your personal assets including your home are at risk. Public liability covers third-party injury and property damage claims arising from your business activities, regardless of whether you operate as a company or as an individual.
For sole traders who are also the primary income earner for their household, personal accident insurance alongside public liability is strongly recommended — PL covers claims made against you, personal accident covers you if you are injured and cannot work. See our guide to sole trader insurance for the full picture.
What is the difference between public liability and professional indemnity?
Public liability covers physical injury and property damage caused by your business operations. Professional indemnity covers financial loss caused by errors, omissions, or negligence in your professional advice or services. They address different types of claims and many businesses need both.
A concrete example: if a building designer's plans contain a structural error that causes a ceiling to collapse injuring a homeowner, that is a professional indemnity claim — the loss arose from incorrect professional advice, not a physical act. If the same designer's site visit causes a trip hazard that injures a client, that is a public liability claim. Professionals who both advise clients and operate physically on their premises — architects, healthcare practitioners, consultants — typically need both covers. See our professional indemnity insurance page for more.
Can I note my landlord as an interested party on my public liability policy?
Yes — most commercial leases require the tenant to note the landlord as an interested party on the certificate of currency. This means the certificate shows both your name as the insured and your landlord's name as an interested party, confirming to the landlord that cover is in place. We add landlord and body corporate notations to certificates at no additional cost. If your landlord has specific wording requirements for the certificate — some large commercial landlords do — provide us with the exact wording required and we will ensure the certificate meets their conditions.
How much does public liability insurance cost?
Public liability insurance cost depends on your industry, annual turnover, number of employees, location, whether you use subcontractors, your claims history, and the limit of cover required. As a general guide for Australian businesses:
Low-risk sole trader or service business: $400 to $800 per year for $5M to $10M cover. Medium-risk trade or retail business: $800 to $2,500 per year for $10M to $20M cover. Higher-risk construction, hospitality, or healthcare: $2,000 to $6,000+ per year depending on turnover and activity. See our detailed public liability insurance cost guide for a full breakdown by industry and turnover band, or contact Lauren for a same-day quote specific to your business.
What is contractual liability and do I need it?
Contractual liability arises when you sign a contract that makes you liable for losses regardless of fault — accepting responsibility for events that would not otherwise be your legal liability. Standard public liability policies exclude contractual liability, meaning if a claim arises from a contractual obligation you have assumed, the policy may not respond.
This is common in construction subcontracts, commercial leases with broad indemnity clauses, and service agreements with large corporate clients. If you sign contracts that include indemnity clauses or hold harmless agreements, have your broker review whether your policy needs a contractual liability extension before you sign. It is a condition that should be confirmed in writing from your insurer rather than assumed to be included.
How do I make a public liability claim?
Contact us as soon as an incident occurs or you receive notification of a potential claim — do not wait until formal legal proceedings are served. Early notification gives your insurer the best opportunity to manage the claim effectively and avoid unnecessary escalation. We manage the claim process on your behalf from first notification through to settlement, including liaising with the insurer, providing documentation, and attending to any legal proceedings that arise.
The information you will need at first notification: date, time and location of the incident, a description of what happened, the identity of any injured parties or damaged property, any witness details, and any photographs or documentation from the scene. Do not make any admissions of liability to the claimant before speaking with us — this can affect how the insurer responds to the claim.
Get the right public liability cover for your business
We compare public liability policies across 150+ Australian insurers to find the right limit, the right wording, and the right insurer for your specific business activities — and issue certificates the same day so your lease, contract, or licence renewal is never held up waiting for paperwork.
