Construction Insurance for Brisbane Builders, Tradies, and Contractors
Brisbane-based specialist construction insurance broker arranging public liability, contract works, and income protection for directors and sole operators across South East Queensland
Construction insurance for Brisbane builders, tradies, and contractors
Morgan Insurance Brokers is based in Brisbane and has been arranging construction insurance for Queensland builders, tradies, and contractors since 2018. We understand the specific risk profile of construction in South East Queensland — from inner-city apartment construction in the CBD through to residential housing estates in Ipswich, Logan, and the Moreton Bay region — and we compare across a specialist panel of construction insurers to find the right cover for your business.
Local knowledge and specialist construction cover for Brisbane builders and tradies
Public liability, contract works, tools, income protection, and personal accident arranged by a Brisbane-based broker
Construction insurance in Brisbane is not a single product. It is a combination of covers that protects your business, your projects, your equipment, and your personal income across the full range of risks that come with running a construction business in South East Queensland. The specific covers you need depend on whether you are a sole operator tradie or run a team, whether you work on residential or commercial projects, and whether you engage subcontractors.
A Brisbane broker who knows construction understands your site access requirements, your subcontract conditions, and the Queensland weather risk
Local knowledge, specialist construction insurers, and same-day certificates for urgent site access requirements
Many online insurance platforms and interstate brokers arrange construction insurance using generic national policy structures that do not account for Queensland-specific conditions — particularly the storm, hail, and flooding exposure that affects Brisbane contract works policies. A Brisbane broker who works with construction businesses every day understands the specific scenarios that affect your cover and finds the policy that responds correctly when something goes wrong.
Construction company directors and sole operator tradies are not covered by workers compensation for their own injuries
Workers compensation covers your employees if they are injured on site. It does not cover you as the business owner, director, or self-employed tradie. If a back injury from heavy lifting, a hand injury from power tools, or a serious illness puts you off the tools, your income stops immediately with no employer safety net and no workers compensation claim available to you.
Income protection insurance replaces up to 70% of your income during your recovery period, covering your mortgage, family expenses, and business fixed costs while you focus on recovering. Personal accident insurance is a faster-paying alternative with shorter waiting periods, suited to directors and sole operator tradies who need income replacement from the first days off work rather than after a waiting period. A broker assesses your specific situation and recommends the right cover for your income level, financial obligations, and how your business is structured. See our income protection page and personal accident page for more detail on each option.
Brisbane construction businesses we insure
We arrange construction insurance for Brisbane and South East Queensland construction businesses across every trade and project type. Here are the most common construction businesses we work with in the Brisbane market.
Brisbane residential builders
Licensed builders constructing homes and townhouses across Brisbane, Ipswich, Logan, Moreton Bay, and the Sunshine Coast hinterland. Public liability, contract works with Queensland storm cover, and income protection for directors arranged with same-day certificates for site access.
Commercial builders and fit-out contractors
Builders and fit-out contractors working on Brisbane CBD commercial projects, office refurbishments, and retail tenancy fit-outs. Higher public liability limits, contract works for commercial projects, and professional indemnity for design input commonly required by Brisbane commercial clients.
Brisbane electricians
Licensed electrical contractors across Brisbane and South East Queensland. Public liability, tools cover, and income protection or personal accident for sole operator electricians who have no employer safety net if a hand injury or illness puts them off the tools. See our dedicated electrician insurance page.
Brisbane plumbers
Licensed plumbing and drainage contractors in Brisbane. Public liability, tools cover, and commercial motor insurance for plumbers running a ute between residential and commercial jobs. Personal accident or income protection for sole operator plumbers with no employer income protection.
Earthmoving and civil contractors
Earthmoving, excavation, and civil construction businesses across Brisbane and the broader South East Queensland region. Underground service strikes, vibration damage to adjacent properties, and high-value plant and equipment all require specialist cover beyond a standard public liability policy.
Concreters and formworkers
Concreting businesses and formwork contractors working on Brisbane residential and commercial projects. High physical injury exposure from heavy lifting and repetitive work makes personal accident cover for sole operator concreters an important complement to their public liability policy.
Roofers and scaffolders
Roofing contractors and scaffolding businesses in Brisbane. Falls from heights create the highest injury risk in the construction industry. Public liability at adequate limits and personal accident or income protection for directors and sole operators are both essential for this trade.
Tradies and subcontractors
Sole operator and small team tradies across all trades working as subcontractors on Brisbane residential and commercial projects. Public liability at the correct limit for your head contractor's requirements, tools cover, and personal accident for sole operators with no employer protection if injured on site.
Owner builders
Owner builders undertaking residential construction in Brisbane and South East Queensland. Public liability from the day you become responsible for the site, contract works for the project itself, and personal accident cover for the duration of the build are all important for owner builders managing their own construction risk.
Construction insurance covers for Brisbane builders and tradies
Here is what each cover does for Brisbane construction businesses, including Queensland-specific considerations that affect how each policy needs to be structured.
Public liability insurance
Site access and subcontract requirementsPublic liability insurance is the foundational cover for any Brisbane construction business. It covers claims from third parties for injury or property damage arising from your construction activities on site. Most principal contractors and commercial project owners in Brisbane require $10M to $20M cover before allowing subcontractors on site, and a current certificate of currency must be produced on request. A broker reviews your subcontract agreement and confirms the specific limit and endorsements required before you start a new project so your documentation is accepted first time without delays to your start date.
Contract works insurance
Queensland storm, hail, and flood exposureContract works insurance covers the physical project during construction against fire, storm, hail, theft, vandalism, and accidental damage. Queensland's elevated exposure to severe storms, hail events, and flooding makes contract works insurance particularly important for Brisbane builders — a summer storm that sets a project back three weeks, or hail that damages a roof under construction, can cost tens of thousands of dollars in re-work without cover in place. Check your policy's storm and flood sub-limits carefully, as some policies carry lower limits for weather events in Queensland's higher-risk zones that could leave your project underinsured after a major event.
Tools and equipment insurance
Theft from Brisbane job sites and vehiclesTools and equipment insurance covers theft, accidental damage, and loss in transit of the tools and equipment your business depends on. Tool theft from vehicles and job sites is one of the most frequent construction insurance claims in Brisbane, particularly in suburban residential construction areas where sites are less secure overnight than inner-city projects. High-value items above the policy's automatic sub-limit need to be individually listed to ensure full replacement cover applies. A broker reviews your total tools value and ensures your policy covers the actual replacement cost of your equipment rather than a depreciated estimate.
Income protection insurance
For Brisbane construction directors and self-employed tradiesIncome protection insurance is the most important personal cover for Brisbane builders, contractors, and tradies who are self-employed or operate as company directors. Workers compensation covers your employees if they are injured on site. It does not cover you. If a back injury from heavy lifting, a hand injury from power tools, or a serious illness prevents you from working, your income stops immediately. Income protection replaces up to 70% of your pre-disability income during your recovery period, covering your mortgage, family expenses, and the fixed costs of keeping your business running while you get back on your feet. Premiums are generally tax-deductible when held outside superannuation.
Personal accident insurance
Fast-paying weekly income for directors and sole operatorsPersonal accident insurance pays a weekly benefit of up to 85% of your income if you are unable to work due to an accidental injury or illness. It is simpler and faster to claim on than income protection, with shorter waiting periods that suit directors and sole operator tradies who need income replacement from the first week off work rather than after a longer waiting period. Many Brisbane construction business owners hold both — personal accident for immediate short-term cover if they are injured, and income protection as the longer-term policy for serious illness or extended injury recovery. A broker assesses your income level, financial obligations, and business structure and recommends the right combination for your specific situation.
Professional indemnity insurance
Design and construct and project managementProfessional indemnity insurance is required for Brisbane builders and contractors working under Design and Construct contracts, where they are responsible for both the design and construction of the project. PI is also increasingly required by commercial clients for larger Brisbane projects even where a formal D&C contract has not been signed, if the contractor provides any design input, specification guidance, or professional advice as part of their scope of work. A standard public liability policy does not cover professional advice claims — only a PI policy responds to these scenarios, and the two covers need to work alongside each other for a construction business with any design responsibility.
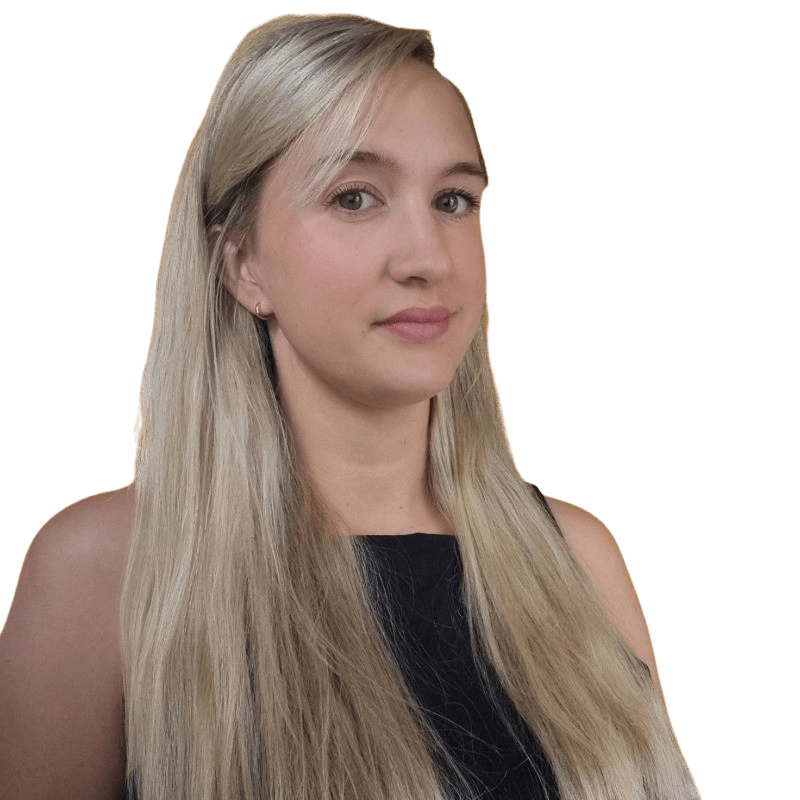
Lauren Spice is the Director of Morgan Insurance Brokers, based in Brisbane at Level 38, 71 Eagle Street. She has been arranging construction insurance for Queensland builders, tradies, and contractors since 2018, with hands-on knowledge of the specific risks, subcontract conditions, and personal insurance gaps that affect construction business owners in South East Queensland's residential and commercial construction market.
One of the most common gaps Lauren identifies when reviewing construction businesses is the personal income exposure of directors and sole operators. Most Brisbane builders and tradies have public liability and tools cover in place but have no income protection if they are injured or become seriously ill. Workers compensation covers their employees — not them. A serious back injury, a hand injury that prevents tool use, or a cancer diagnosis can stop a construction business owner's income entirely while their financial obligations continue. Lauren reviews your personal financial position alongside your business insurance and structures income protection or personal accident cover that reflects your income level and how your business is set up.
When a claim arises Lauren's team manages the process from first notification through to settlement, advocating for the client with the insurer and coordinating across all affected policies so you are not left managing multiple insurers yourself during what is already a difficult period.
Brisbane construction insurance FAQs
The questions we are most commonly asked by Brisbane builders, tradies, and contractors when arranging or reviewing their construction insurance.
Am I covered by workers compensation as the owner of my construction business?
No. Workers compensation covers your employees for work-related injuries and illnesses. It does not cover you as the business owner, director, or self-employed tradie. If you are injured on a job site or become seriously ill and cannot work, there is no workers compensation claim available to you — regardless of how seriously you are injured or how long you are off work.
This is one of the most significant and most overlooked insurance gaps for Brisbane construction business owners. The two main options are income protection insurance, which replaces up to 70% of your income during a longer recovery period and is generally tax-deductible, and personal accident insurance, which pays a weekly benefit faster and with shorter waiting periods. Many Brisbane builders and tradies hold both. A broker assesses your situation and recommends the right combination for your income level and financial obligations.
Is contract works insurance more important in Queensland than other states?
Contract works insurance is important everywhere, but Queensland's elevated exposure to severe storm, hail, and flooding events makes it particularly critical for Brisbane builders and contractors. South East Queensland regularly experiences severe hailstorms during summer that can cause significant damage to partially built structures, roofing under construction, and building materials stored on site.
Two things to check on your contract works policy if you are building in Queensland. First, the storm and weather event sub-limits — some policies apply lower limits for storm and flood damage in certain Queensland postcodes. Second, the flood definition — there is an important distinction between storm-surge flooding and rainwater flooding in policy wording, and both need to be covered for Brisbane projects near waterways or in low-lying areas. A broker reviews these conditions for your specific project locations before recommending a policy.
What is the difference between income protection and personal accident for a Brisbane tradie?
Both covers replace your income if you cannot work due to injury or illness, but they work differently and suit different needs.
Personal accident insurance typically has shorter waiting periods — sometimes as little as one day — is simpler to claim on, and pays a weekly benefit of up to 85% of your income. It is suited to sole operator tradies and directors who need income replacement quickly if they are injured. Premiums are generally not tax-deductible.
Income protection insurance covers a broader range of conditions, offers benefit periods of up to age 65, and premiums are generally tax-deductible when held outside superannuation. The own occupation definition is particularly valuable for tradies — it pays if you cannot perform your specific trade, not just any work at all. An electrician with a hand tremor or a roofer with a significant knee injury would be covered under own occupation even if they could theoretically do administrative work. Many Brisbane construction business owners hold both covers working together — personal accident as the immediate short-term safety net and income protection as the long-term serious illness cover.
Does my insurance cover me for projects outside Brisbane?
Most public liability and contract works policies arranged through a broker cover you Australia-wide as standard, so taking on a project in regional Queensland, the Gold Coast, Sunshine Coast, Toowoomba, or interstate is covered without needing a separate policy.
Confirm with your broker if you take on projects in cyclone-prone regions of Queensland — Far North Queensland, North Queensland, and coastal areas above the Tropic of Capricorn have elevated cyclone risk and some contract works policies apply specific conditions or sub-limits for cyclone damage in these areas. A broker confirms the geographic scope of your policy and any regional conditions before you accept a project outside your usual Brisbane and South East Queensland market.
What insurance do I need as a subcontractor on a Brisbane project?
As a subcontractor on a Brisbane project, the minimum insurance you will almost always need before site access is granted is current public liability insurance at the limit specified in your subcontract agreement — typically $10M or $20M depending on the principal contractor's requirements. Most Brisbane head contractors require your certificate of currency before your first day on site.
Do not assume the principal contractor's policy covers you. Their contract works policy covers the project itself but may not extend to your specific scope of work as a subcontractor. Their public liability covers their own liability, not yours. As a self-employed subcontractor you also have no workers compensation protection for your own injuries — personal accident insurance fills this gap. Send us your subcontract agreement and we will confirm what is required and issue the correct documentation before your start date.
How much does construction insurance cost in Brisbane?
Construction insurance costs in Brisbane vary based on your trade, annual turnover, the number of employees, project values, and the specific covers required. As a general guide for Brisbane and South East Queensland:
Public liability at $10M for a sole operator tradie typically starts from $600 to $1,500 per year. Higher-risk trades such as roofing, demolition, and scaffolding attract higher premiums. Contract works cover is typically priced as a percentage of the contract value, commonly 0.15% to 0.35% depending on project type, build duration, and Queensland weather exposure. Personal accident for a Brisbane tradie typically starts from $500 to $1,500 per year depending on age, income, and the weekly benefit selected. Income protection typically costs $800 to $2,500 per year depending on age, income level, waiting period, and benefit period.
The most accurate way to understand your cost is to have a Brisbane broker compare across specialist construction insurers for your specific trade profile. Contact us for a same-day indicative quote. See our construction insurance cost guide for more detail on what drives your premium.
Based in Brisbane and need a construction insurance quote today? We issue certificates the same day for most construction insurance enquiries.
Get a Brisbane construction quoteReady to protect your Brisbane construction business?
Whether you are a sole operator tradie needing public liability for a new subcontract or a construction company managing multiple crews and directors who need their personal income protected, we are based in Brisbane and compare specialist construction insurers to find the right cover for your business.
